
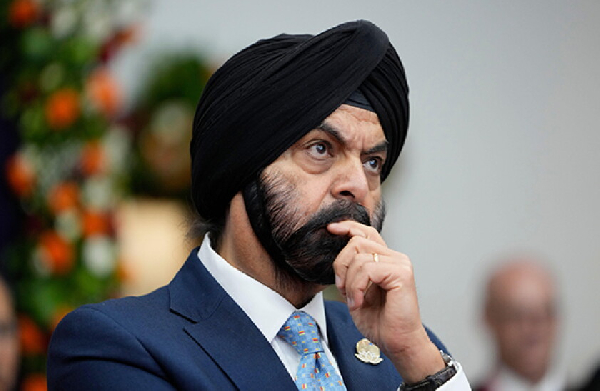
The world could face a major employment challenge over the next 10 to 15 years, with hundreds of millions of young people at risk of entering the labour market without jobs, according to World Bank President Ajay Banga.
Banga warned that about 1.2 billion young people are expected to reach working age during the period, while only around 400 million jobs are projected to be available. This could leave a shortfall of approximately 800 million jobs, highlighting the urgent need for countries to accelerate employment creation.
He made the remarks at the 2026 World Bank and International Monetary Fund Annual Meetings Plenary, where he called for stronger efforts to expand job opportunities and improve the use of limited development resources.
Banga said decisions being taken today would have lasting consequences for an entire generation, making employment creation a priority for governments and development partners.
“The choices we make today will help determine how,” he said, although the statement provided did not include the completion of the remark.
He stressed that addressing the potential jobs gap would require governments, private investors, philanthropic organisations and technology providers to work together, with their efforts tailored to the needs of individual countries.
The World Bank’s jobs strategy, he explained, is built around three key areas: improving infrastructure and public services, establishing clear and predictable policies, and mobilising investment on a much larger scale.
Banga said businesses need reliable electricity, water supplies, transport systems and digital connectivity to grow and create jobs. Workers, meanwhile, require access to healthcare, education and skills that match the demands of the labour market.
He disclosed that the World Bank committed $40 billion to these foundations last year, representing nearly one-third of its total financing.
Beyond its focus on employment, Banga outlined reforms aimed at making the institution more efficient and better equipped to support development projects.
According to him, the Bank has reduced the time required to prepare projects from 19 months to nine months. It has also increased the share of its financing linked to measurable results from about one-third to half.
Changes to the institution’s balance sheet have created more than $100 billion in additional lending capacity over a decade, he added.
The Bank has also increased its efforts to mobilise private investment. Banga said private capital mobilised through the institution rose from approximately $35 billion in 2022 to $112 billion last year.
When combined with the World Bank’s own financing, total financing exceeded $230 billion, he said.
Banga argued that the reforms had strengthened the Bank’s capacity to support development, while its jobs strategy provided a clearer direction for its work.
“Taken together, these changes give us greater capacity. Our jobs strategy gives it direction,” he said.
The projected employment shortfall presents a significant challenge for countries seeking to provide opportunities for growing numbers of young people. Banga’s remarks underscored the need for stronger investment, better public services and closer cooperation between governments and the private sector to expand employment opportunities over the coming years.